Whether commuting via I-70 to Indianapolis or working near the local warehouse district, deciding how to pay for your next vehicle is a crucial step. Choosing between an auto loan or a lease depends heavily on your daily mileage and long-term driving goals. For decades, Andy Mohr Chevrolet has been a trusted automotive partner for drivers across Plainfield, IN, and nearby Avon, Brownsburg, and Greenwood. Our dedicated team not only guides you through payment choices, but we also provide expert, long-term service and maintenance to keep your Chevrolet vehicles running reliably year after year. As your local dealership team, we have guided thousands of our neighbors toward clear, practical financing solutions tailored to their everyday routines.
Key Takeaways (TL; DR)
Navigating the world of auto financing does not have to be an overwhelming process. For drivers across Plainfield and the greater Indianapolis area, securing the right auto loan or lease simply comes down to understanding your credit profile, exploring GM Financial offers, and knowing whether long-term ownership or lower monthly payments fits your daily routine best. Here is a quick breakdown of the most critical factors to keep in mind before you sign on the dotted line.
- Your Credit Profile Sets the Pace: Your credit history directly influences the Annual Percentage Rate (APR) you qualify for. Higher scores generally unlock the most competitive rates, meaning you pay significantly less in interest over the life of your vehicle loan.
- GM Financial Incentives: As Chevrolet's official financing arm, GM Financial frequently provides exclusive promotional rates and streamlined pre-approval. This makes locking in terms for a new Silverado 1500 before heading to a shift in the Plainfield warehouse district much faster.
- Financing Builds Equity, Leasing Lowers Payments: Taking out a traditional loan means you eventually own the vehicle outright, which is ideal if you rack up high mileage commuting on I-70. Leasing a model like the Chevrolet Equinox acts more like a long-term rental, typically keeping monthly costs down while keeping you safely under the factory 3-year/36,000-mile Bumper-to-Bumper Limited Warranty.
- End-of-Term Choices: When a lease concludes, you aren't locked into a single path. You have the flexibility to purchase your current vehicle, upgrade to the newest model year, or simply hand the keys back before grabbing dinner near the Shops at Perry Crossing.
- Chevrolet Discount Programs: Eligible drivers can often stack special factory offers to lower their total financed amount. Programs for military members, first responders, educators, and college graduates can act as a helpful multiplier alongside your down payment.
- Gather Your Documents Early: Arriving prepared with your recent pay stubs, valid driver's license, proof of insurance, and a clear budget significantly speeds up the paperwork process, getting you back out on U.S. Route 40 without unnecessary delays.
How Chevrolet Financing Works
Automotive financing simply means borrowing money from a lender-such as a local Indiana credit union, a bank, or GM Financial-to cover the purchase price of your Chevrolet. You then pay back that principal amount plus interest in set monthly installments over an agreed-upon duration, known as your loan term. Standard auto loan terms typically range between 48 and 72 months. What this means for Plainfield drivers is that you can secure a fuel-efficient commuter like the Chevrolet Trax for daily trips into Indianapolis via I-70 without needing the entire vehicle cost upfront.
As you make those predictable monthly payments, you steadily build equity, which represents the actual cash value of the vehicle you own out-right. Once the balance hits zero, the lender officially transfers the title to your name, making the car entirely yours. For example, if your routine involves heavy driving through the warehouse district near the Indianapolis International Airport or hauling supplies along U.S. Route 40, a financed Chevrolet Silverado 1500 gives you the freedom to rack up unlimited miles and permanently modify the truck bed however you see fit. Ultimately, taking out a loan is the most straightforward path to long-term ownership for drivers who want a dependable vehicle they can keep for years.
Navigating GM Financial for Your Chevrolet

GM Financial serves as the dedicated lending arm for Chevrolet, streamlining the way you purchase or lease your next vehicle. Whether you are eyeing a 2027 Chevrolet Equinox for family errands near The Shops at Perry Crossing or need a Silverado 1500 for heavy lifting in the warehouse district on the east side, securing a competitive auto loan matters. GM Financial frequently provides dealership-exclusive incentives-such as promotional Annual Percentage Rates (APRs) or flexible 24- to 84-month loan terms-that traditional outside banks may not match. For Plainfield drivers, this means a more straightforward path from the showroom floor to your driveway, structured around your actual monthly budget.
The application process is built for modern convenience. You can apply for financing directly at the dealership or use a secure online pre-approval tool before you even leave your house. Tackling your pre-approval online usually saves about 45 minutes of paperwork at the desk, letting you spend that time test-driving instead of waiting in a chair. GM Financial evaluates factors like your income and credit history to determine your exact loan or lease eligibility, meaning final offers and interest rates will always vary by credit. Ultimately, locking in the right financing gives you a predictable payment structure, keeping your daily commute down Interstate 70 as smooth and stress-free as possible.
Understanding How a Chevrolet Lease Works
Instead of buying a vehicle outright, leasing a Chevrolet operates much like a long-term contract where you pay for the car's use over a set timeframe, typically lasting between 24 and 36 months. Over this period, your monthly payments cover the vehicle's depreciation rather than its entire sticker price. This depreciation is calculated by taking the original cost and subtracting the expected worth at the end of your contract-a figure known as the residual value. Alongside this, your payment includes a money factor, which is essentially the lease version of an interest rate. For drivers in Plainfield, this structure matters because it generally results in a lower monthly financial commitment compared to traditional financing, keeping your transportation budget highly predictable.
If you regularly navigate the morning rush on I-70 into Indianapolis or load up the family for a weekend trip to The Shops at Perry Crossing, leasing allows you to drive a modern vehicle without a long-term commitment. Comparing the structure is straightforward: rather than taking out a five-year loan on the total purchase price of a new Chevrolet Equinox, a 36-month lease charges you only for the exact portion of the vehicle's lifespan you use. Because standard lease terms rarely exceed three years, they perfectly align with the new Chevrolet 3-year/36,000-mile Bumper-to-Bumper Limited Warranty. That means you drive under factory protection for the vast majority of your lease, minimizing the risk of out-of-pocket repair costs while enjoying updated tech and safety features.
Deciding What to Do When Your Chevrolet Lease Ends
As your contract begins to wind down, you have three primary paths forward: buying your current ride, upgrading to a new model, or simply handing the keys back. For Plainfield drivers navigating the daily commute on Interstate 70 or making weekend shopping trips to the Metropolis Mall, this built-in flexibility means you can easily adapt your transportation to match your evolving lifestyle.
- Purchase Your Current Leased Chevrolet: If you have grown attached to your Chevrolet Equinox after years of reliable school drop-offs near White Lick Creek, you can buy it outright. You will pay the exact residual value locked in during your original lease signing, allowing you to keep a proven vehicle without worrying about current market markups.
- Upgrade to a New Chevrolet: Ready for the newest features or perhaps a larger cabin? You can seamlessly return your current ride and start a fresh lease or financing plan. Upgrading to a brand-new Chevrolet Traverse, for instance, unlocks the latest standard safety technologies to help you feel more confident driving down U.S. Route 40.
- Return Your Vehicle: If you no longer need a daily driver, you can easily walk away. You will just need to schedule a quick, professional inspection beforehand to document the condition. Addressing any excessive wear, tear, or mileage overages ahead of time ensures a smooth, penalty-free transition when you turn in the keys.
Chevrolet Financing vs. Leasing: Which Fits Your Daily Drive?

The main difference between buying and leasing is ownership status. When you finance a Chevrolet Silverado 1500, you build equity with every payment. Leasing an Equinox EV means paying only for expected depreciation. For Plainfield drivers taking I-70 into Indianapolis, leasing often means lower monthly costs, while financing provides the freedom of unlimited miles.
| Feature | Financing a Chevrolet | Leasing a Chevrolet |
|---|---|---|
| Ownership | The title officially transfers to your name after the final loan payment. | The lending institution retains ownership of the vehicle throughout the contract. |
| Monthly Payments | Generally higher, because your payments are based on the full negotiated price of the vehicle. | Usually lower, since you are only paying for the vehicle's calculated depreciation over a set 24- to 36-month term. |
| Upfront Costs | A substantial down payment is typically recommended to reduce your total loan amount and long-term interest. | Usually requires the first month's payment, an acquisition fee, and sometimes a security deposit due at signing. |
| Customization | You have complete freedom to add a tonneau cover to your Colorado or install aftermarket wheels. | The vehicle must remain in its original factory condition; permanent modifications are not permitted. |
| Mileage | No restrictions. Drive as much as you want, whether that means endless local errands or daily trips to the warehouse district near the airport. | Subject to strict annual mileage caps (often 10,000 to 15,000 miles), with per-mile overage penalties if you exceed the limit. |
| Wear & Tear | Dings and scratches are yours to manage. They only matter by eventually lowering your future trade-in or resale value. | You may be charged out-of-pocket penalty fees at the end of the term for any damage beyond normal use. |
| End of Term | Keep driving payment-free, sell it privately, or use its equity as a trade-in for your next vehicle. | Turn the keys in, buy it out for its remaining residual value, or roll into a brand-new lease. |
What Shapes Your Chevrolet Finance and Lease Rates?
Getting the keys to a new Chevrolet involves several personal and financial variables that directly determine your final APR and monthly payment. For drivers around Plainfield, understanding how lenders weigh your credit, income, and vehicle choice means you can structure a plan that comfortably fits your household budget-whether you are leasing a fuel-efficient Chevrolet Trax for daily commutes down U.S. Route 40 or financing a spacious Suburban for weekend errands near Metropolis Mall. It is essentially a balancing act between the upfront capital you provide and the timeline you choose to pay it off. For instance, stretching an auto loan from 48 months to 72 months on a new Chevrolet Equinox drastically lowers your immediate monthly cost, but it naturally increases the total interest paid over the life of the vehicle.
- Credit Profile: A strong credit score serves as your financial resume. Higher rating tiers typically unlock Chevrolet's most competitive promotional interest rates.
- Down Payment Size: Bringing cash to the table or applying trade-in equity directly reduces your principal loan amount, which lowers both your monthly obligation and the total interest accrued.
- Term Length: Standard auto loans generally range from 36 to 84 months. Shorter agreements save money on interest, while longer terms provide maximum flexibility for your checking account.
- Vehicle Choice and Promotions: Factory incentives fluctuate based on the specific model, body style, and whether it is new or used. A brand-new Silverado 1500 gas truck often features different subvented finance rates than a certified pre-owned vehicle.
- Debt-to-Income (DTI) Ratio: Lenders compare your existing monthly debts to your gross income to ensure a new car payment remains manageable alongside your everyday living expenses.
Are There Special Chevrolet Discount Programs I Can Use?
Yes, there are several targeted discount and financing programs available that can significantly lower your bottom line when purchasing or leasing a new vehicle. By verifying your eligibility through Chevrolet or working with our finance department, you can frequently stack manufacturer rebates with current dealership incentives. Whether you are hauling heavy supplies to the warehouse district near the Indianapolis International Airport in a new Chevrolet Silverado 1500 Gas truck, or managing the daily school drop-off routine along Quaker Boulevard in a spacious Chevrolet Equinox Gas SUV, securing the best rate matters for keeping your monthly budget predictable. For example, qualifying for a targeted cash allowance rather than relying on standard financing alone can sometimes free up enough budget to bump up to a higher trim level with advanced safety technology.
- Chevrolet College Discount: Recent graduates and eligible college students can often secure special pricing that falls below standard MSRP. By simply providing a recent diploma or proof of current enrollment, younger drivers can more easily afford a reliable, efficient vehicle right before starting a new career in downtown Indianapolis.
- Military Appreciation Offers: Active duty service members, reservists, veterans within one year of discharge, and their spouses may qualify for exclusive cash allowances. Presenting a valid military ID or your Leave and Earnings Statement (LES) unlocks these savings, providing a well-deserved financial break for those serving our country and returning home to Hendricks County.
- Owner Loyalty Benefits: If you already have an eligible vehicle from the brand parked in your garage, you might qualify for loyalty cash or lease pull-ahead incentives when it is time for an upgrade. This means returning drivers can often transition into the latest model year while maintaining a comfortable monthly payment, making your next family trip to The Shops at Perry Crossing that much sweeter.
- Regional and Dealer Promotions: Manufacturer incentives change based on the season and local market demands. You will frequently see limited-time APR specials or customized lease deals aimed directly at Midwest drivers, helping you get behind the wheel of a dependable vehicle ready to tackle winter commutes down U.S. Route 40.
Securing Your Chevrolet Lease or Auto Loan

Wondering how to kickstart the paperwork for a versatile Chevrolet Equinox or a hardworking Silverado 1500? Whether you are weighing a 36-month lease to keep your monthly costs predictable or a traditional 60-month auto loan for long-term ownership, the entire process is built around your schedule. For drivers commuting down Quaker Boulevard or heading to shifts in the warehouse district near the Indianapolis International Airport, having a streamlined application process matters because it gets you off the lot and back to your daily routine much faster. You can easily start these steps from the comfort of your living room and wrap everything up with our finance experts in person.
- Check Your Pre-Qualification: See your likely purchasing power and estimate potential Annual Percentage Rates (APR) before taking a test drive. This initial step uses a soft inquiry, letting you build a budget framework without affecting your current credit score.
- Gather Essential Documents: Lenders need to verify your identity and financial standing. Be sure to have your valid driver's license, recent pay stubs or alternative proof of income, proof of your local residence, and active auto insurance information ready to go.
- Submit the Official Application: Once you pinpoint the exact Chevrolet model you want to take home, you will complete the full financing application. Keep in mind that a hard credit pull is required at this stage so lenders can officially lock in your final rates and term limits.
- Review the Terms and Sign: Carefully read through the approved APR, your exact monthly payment, and the duration of the loan or lease. If you opted for an extended Chevrolet Protection Plan to add peace of mind to those unpredictable winter commutes on I-70, confirm those coverages are correct before signing the final dotted line.
Should You Buy Outright or Take Out a Loan?
Handing over a check for your vehicle outright means you get the title on day one, skipping interest charges entirely. For families shopping near The Shops at Perry Crossing, paying cash for a gas-powered SUV like the Chevrolet Traverse offers the immediate peace of mind that comes with zero monthly car payments. That said, writing one large check drains a significant portion of your liquid savings. What this means for Plainfield drivers is you must balance the comfort of outright ownership against tying up funds you might need later for home maintenance or an unexpected emergency.
On the flip side, financing allows you to spread the cost over several years while keeping your bank account intact. If you commute to Indianapolis via Interstate 70, securing a loan for a highly capable truck like the Chevrolet Silverado 1500 or the all-electric Chevrolet Silverado EV means you can handle daily logistics without emptying your savings up front. Breaking down the total into manageable chunks-say, a predictable monthly payment versus a massive lump sum-often makes it easier to fit a dependable vehicle into your current lifestyle. The right path simply depends on your comfort level with monthly bills and your long-term budget goals.
What Are the Pros and Cons of Each Payment Method?
Deciding whether to buy or lease depends entirely on your driving habits. For Plainfield drivers, this means balancing long-term equity with flexibility. Financing a 2027 Chevrolet Silverado 1500 builds ownership for jobs near the airport, while a 10,000-mile lease on a 2027 Equinox keeps payments lower for Quaker Boulevard school runs.
Pros of Financing a Chevrolet
- Total Ownership: Once that final payment clears, the SUV or truck is 100% yours to keep, sell, or trade.
- Zero Mileage Limits: If your daily route takes you back and forth to Indianapolis on I-70, you won't have to stress about exceeding an annual mileage cap.
- Customization Freedom: Want to add a heavy-duty bed liner or tool rack to your Colorado? Buying allows you to modify your truck exactly how you need it.
- Equity Growth: Every monthly installment builds your financial stake in the vehicle, giving you trade-in leverage later.
Cons of Financing a Chevrolet
- Larger Monthly Commitment: Loan payments are typically higher than lease payments since you are paying off the entire purchase price rather than just the depreciation.
- Post-Warranty Repairs: Once the standard 3-year/36,000-mile Bumper-to-Bumper Limited Warranty expires, mechanical upkeep comes out of pocket.
- Market Depreciation: A vehicle's resale value naturally decreases over time, which impacts your overall return when it is time to sell.
Pros of Leasing a Chevrolet
- More Affordable Payments: Paying only for expected depreciation usually keeps monthly costs lower than financing the exact same model.
- Frequent Upgrades: Turning in a lease every few years means you regularly enjoy the newest safety and technology features for your family trips to the Shops at Perry Crossing.
- Warranty Peace of Mind: Most lease terms last two or three years, aligning perfectly with factory warranties so major repair bills are rarely a concern.
- Hassle-Free Returns: At the contract's end, you simply hand the keys back to the dealership without navigating the private resale market.
Cons of Leasing a Chevrolet
- No Built-In Equity: You don't own the vehicle, meaning you won't have an asset to trade in or sell when the contract wraps up.
- Strict Mileage Caps: Selecting a 10,000-mile limit versus a 15,000-mile limit changes your monthly cost, and miscalculating your daily drive to Greenwood or Brownsburg will lead to per-mile overage fees at turn-in.
- Wear and Use Charges: Dents, deep scratches, or interior stains beyond standard daily wear will result in extra financial penalties.
- Factory Condition Required: You must return the vehicle exactly as it left the lot, making aftermarket modifications impossible.
Smart Strategies for Securing a Great Price
Before you start browsing the lots near The Shops at Perry Crossing, having a solid game plan can drastically reduce your total out-of-pocket expenses. Securing a great deal goes far beyond simple haggling; it requires knowing your financial baseline, timing the local market, and separating the raw vehicle cost from the loan mechanics. For drivers around Plainfield, this means understanding specifics like your Annual Percentage Rate (APR) or a lease's capitalized cost. Mastering these details ensures you can take home a dependable Chevrolet-like a spacious Traverse or an efficient Trax-without overstretching your household budget.
- Review Your Credit Report Early: Well before applying for a loan, check your score for unexpected errors. A quick correction can bump you into a better credit tier, which easily lowers your APR by a few percentage points and saves hundreds over a standard 60-month term.
- Shop Around for Rates: Secure pre-approval from a local bank or credit union before checking dealership financing. Sometimes, promotional manufacturer rates on a new Chevrolet Silverado 1500 or Equinox might beat your local lender, but having that external quote guarantees you possess a competitive baseline.
- Target Strategic Buying Windows: If you commute daily via U.S. Route 40 and have the flexibility to wait, timing your purchase is a highly effective tool. Dealerships frequently push to meet internal targets at the end of the month or quarter, and the arrival of a new model year often triggers incentives on outgoing inventory.
- Focus on the Vehicle's Purchase Price First: Instead of negotiating based on a target monthly payment, pin down the final cost of the vehicle itself. Rolling taxes, fees, and the car's sticker price into a single payment discussion can obscure the actual deal, so establish the core price before shifting to term lengths or trade-in values.
- Learn the Jargon: Understanding auto finance vocabulary protects your wallet. If you prefer to lease a Chevrolet Blazer for predictable monthly costs, familiarize yourself with terms like capitalized cost (the negotiated value of the vehicle), money factor (the interest rate), and residual value (what the car is worth when the lease ends).
- Verify Fair Market Values: Always cross-reference what other buyers in the Indianapolis metro area are currently paying. Independent automotive sites like Kelley Blue Book and Edmunds provide objective pricing data based on real regional sales, giving you a firm anchor during your discussions.
Frequently Asked Questions (FAQs)
What should I ask about financing options?
Andy Mohr Chevrolet's team, including our Spanish-speaking staff, will guide you through our no-haggle pricing structure to ensure an exceptional car-buying experience. We review all financing details transparently so families commuting to Indianapolis or working in the local warehouse district can find a seamless solution for their new Chevrolet.
How can I ensure I understand all fees associated with my loan?
The team at Andy Mohr Chevrolet prioritizes complete transparency with our no-haggle pricing policy, guaranteeing you see every detail of your transaction. Our staff will walk you through the paperwork during your visit or via our Mohr to Your Door virtual tours, keeping the process straightforward for busy Plainfield professionals.
How does Andy Mohr Chevrolet handle post-sale communication and support?
Our commitment to an exceptional car-buying experience includes a complimentary orientation session offered through our Mohr to Your Door program. The family-owned team at Andy Mohr Chevrolet remains fully available to answer any questions, ensuring your new vehicle perfectly supports routine drives along U.S. 40 and I-70.
How do I verify the accuracy of my financing paperwork?
Andy Mohr Chevrolet ensures a seamless process by having our dedicated team review every detail of your no-haggle pricing agreement alongside you. Whether you finalize documents in our family-friendly dealership or at home via our Mohr to Your Door delivery, we make sure everything is accurate and clear before you take the keys.
How does Andy Mohr Chevrolet support the local Plainfield community?
Andy Mohr Chevrolet actively supports local initiatives like the Teddy Drive and Toys for Tots, emphasizing our values of care and connection since 1996. We cherish our community roots by giving back to the families who rely on our dependable Chevrolet SUVs for daily shopping runs to The Shops at Perry Crossing.
What awards has Andy Mohr Chevrolet received for customer satisfaction?
Andy Mohr Chevrolet is proud to be recognized by Cars.com for four consecutive years, highlighting our dedication to providing an exceptional, transparent car-buying experience. Our eco-friendly practices and welcoming atmosphere for families and pets alike reflect the everyday commitment that earned our dealership these accolades.
About Andy Mohr Chevrolet
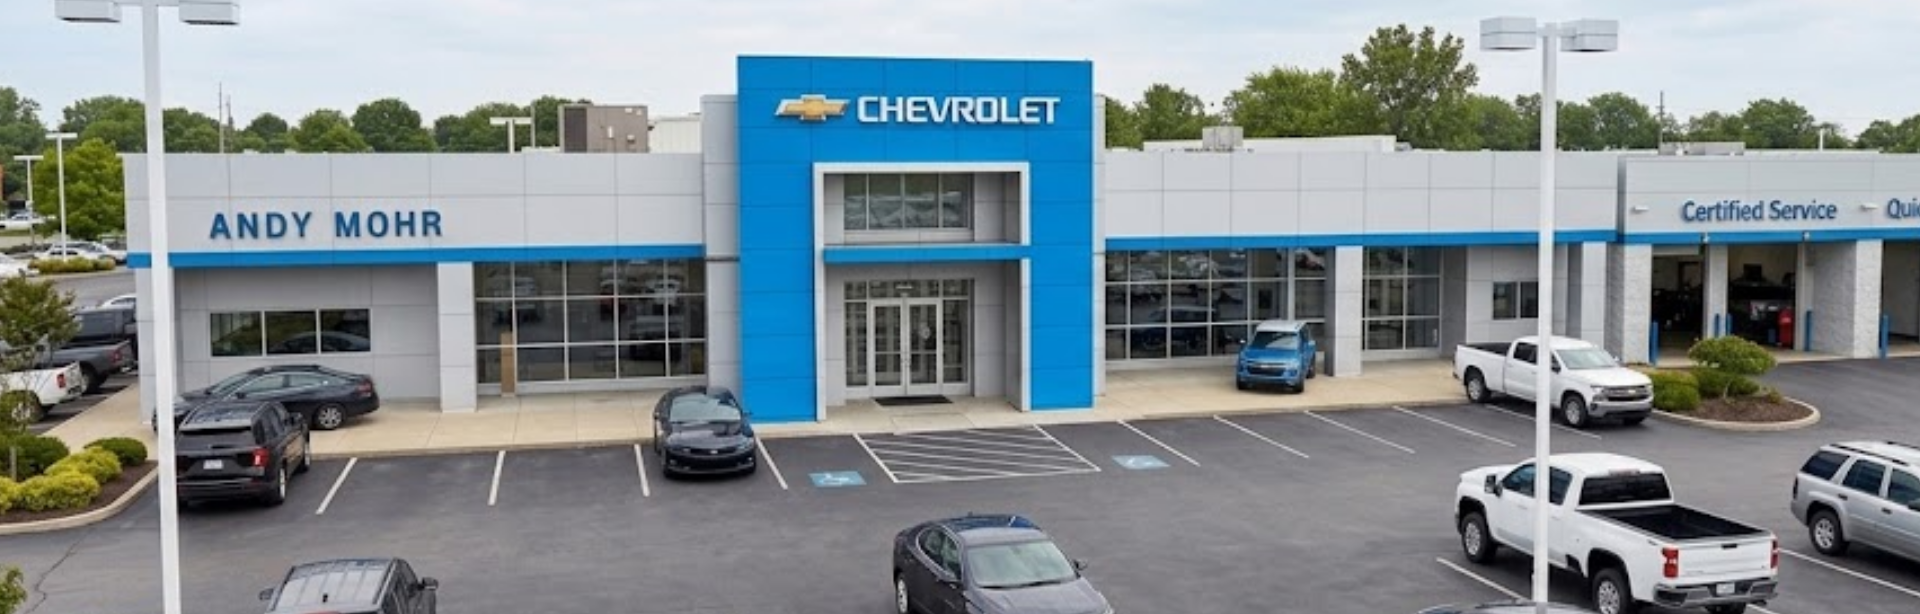
At Andy Mohr Chevrolet, we've proudly served the Plainfield area since 1996 as a family-owned dealership dedicated to providing an exceptional car-buying experience. Our Mohr to Your Door program exemplifies our commitment to convenience and transparency, offering everything from virtual tours to home delivery, all capped with a complimentary orientation session. We cherish our community roots, actively supporting local initiatives like Toys for Tots and the Teddy Drive, emphasizing our values of care and connection. Our award-winning dealership, recognized by Cars.com for four consecutive years, prioritizes customer satisfaction with no-haggle pricing, eco-friendly practices, and a welcoming atmosphere for families and pets alike. Whether buying or servicing, our team, including Spanish-speaking staff and factory-trained technicians, is here to ensure your experience is seamless and enjoyable, every step of the way.Related Articles:
Finding the Top Chevrolet Dealer in Plainfield, IN: A Comprehensive Guide